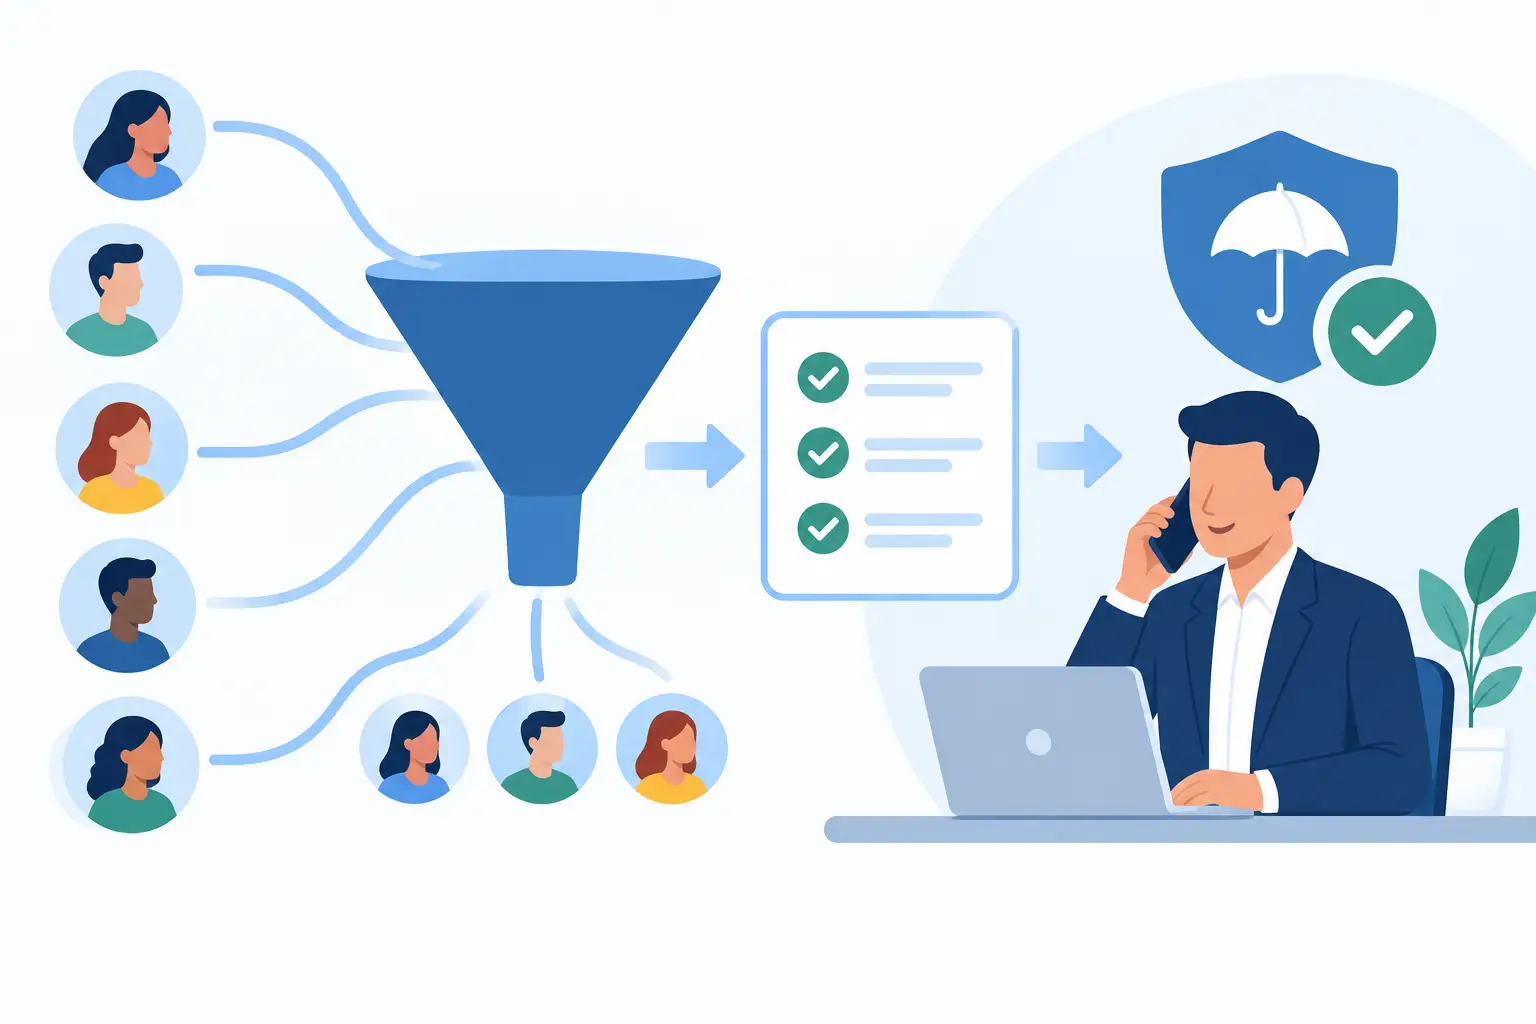
A lead form submission is not a sales opportunity. In insurance, that gap is where margins disappear. A consumer can request a quote with no current policy, no buying authority, an invalid phone number, or no intention of speaking with an agent. To qualify insurance leads effectively, you need to identify who can buy, who is ready to act, and who your team can actually reach before costly sales labor is spent.
The goal is not to reject every imperfect prospect. It is to route the right prospects to the right sales motion, protect agent talk time, and make your acquisition cost produce bindable business.
What Makes an Insurance Lead Qualified?
A qualified insurance lead meets a defined standard for fit, intent, timing, and contactability. The exact threshold depends on the line of business, carrier appetite, geography, and sales model. A life insurance lead and an auto insurance lead should not be scored the same way. Neither should a live transfer and an aged internet lead.
Start with fit. The prospect must be eligible for the product you sell. For auto insurance, that can mean a valid ZIP code, licensed driver status, vehicle details, and coverage needs within your carrier mix. For health insurance, it may include state, age, household information, enrollment timing, and whether the consumer is seeking a qualifying plan type.
Intent comes next. Did the consumer actively request quotes, or did they enter a sweepstakes-style form and consent to marketing as an afterthought? High-intent leads typically show clear shopping behavior: they requested insurance information, completed relevant fields, chose a coverage category, and agreed to be contacted.
Timing separates a future opportunity from an immediate sales conversation. Someone whose policy renews next week deserves a different response than someone who says they are “just looking” and will revisit coverage in six months. Both may have value, but only one belongs in an urgent call queue.
Finally, a lead has to be reachable. Accurate phone numbers, verified contact data, appropriate consent, and fast response windows matter. A perfectly matched prospect is worth little if your agents cannot connect with them.
Qualify Insurance Leads With Questions That Predict a Quote
Every question in your lead flow should earn its place. Long forms can reduce completion rates. Short forms can send sales teams too much noise. The right approach is to ask for the minimum information needed to determine eligibility and prioritize follow-up.
For most insurance campaigns, qualification should establish the prospect’s location, product need, basic risk or household profile, current coverage situation, renewal or purchase timeline, and preferred contact method. It should also confirm that the consumer understands they are requesting insurance information, not simply entering to win something or downloading unrelated content.
Use progressive qualification when more detail is needed. Capture the core facts on the initial form, then collect secondary information through a confirmation page, SMS exchange, verification call, or live transfer flow. This reduces friction without forcing agents to start every conversation from zero.
Ask About the Current Policy Situation
A consumer’s current policy status often reveals urgency faster than a generic question about interest. Are they uninsured? Are they facing a premium increase? Did they recently buy a vehicle or move to a new state? Is their policy renewing within 30 days?
These answers create useful sales context. A prospect trying to replace canceled coverage requires fast, informed handling. A prospect comparing rates ahead of a renewal may be an excellent lead, but the follow-up sequence should match their decision timeline.
Capture Decision-Making Authority
The person filling out the form is not always the person who can approve coverage. For household policies, commercial insurance, or family health plans, establish whether the prospect is the policyholder or a decision-maker. This is especially valuable for call centers where agent time is measured closely.
Do not overcomplicate the question. A simple prompt about who makes insurance decisions can prevent repeated follow-ups to a contact who cannot move the purchase forward.
Confirm Contact Preferences and Consent
Contactability is not just a data issue. It is an operational and compliance issue. Your process should capture the required consent language, timestamp, source, IP data where applicable, and contact preferences needed for your outreach model.
A lead supplier should provide transparent delivery details. If you cannot see when the lead was generated, what form it completed, the source channel, and what it consented to, your team is operating blind. That lack of visibility makes it harder to optimize campaigns and harder to protect your operation.
Score Leads by Revenue Potential, Not Form Completion
A completed form should not automatically receive the same value as every other completed form. Scoring gives your team a practical way to separate immediate opportunities from leads that need nurturing.
A simple scoring model can assign weight to factors such as policy renewal date, verified phone status, product fit, geographic eligibility, requested coverage, current premium pain, and stated purchase timeframe. A prospect with a verified number, an expiring policy, and an active quote request should rise to the top of the queue.
The point is not to build an overly complicated model nobody uses. Start with the factors that have a proven connection to contact rate, quote rate, and bind rate. Review results weekly. If leads marked as “high intent” are not producing quotes, the scoring rules or lead source need attention.
Your CRM should support this process with clear statuses. Avoid vague labels such as “good lead” or “bad lead.” Track reasons for rejection and disposition: out of market, duplicate, invalid contact data, no current need, ineligible risk, no answer, quoted, or bound. This feedback is what allows media buyers and lead partners to improve quality instead of merely increasing volume.
Speed to Lead Is Part of Qualification
The value of an insurance lead declines quickly after submission. A consumer comparing policies may submit multiple quote requests in a short window. The first agent to make relevant contact often gets the best chance to quote and close.
That is why live transfers can outperform standard web leads for campaigns that need immediate conversations. The consumer has already shown intent, completed initial screening, and agreed to speak with an agent. A real-time internet lead can also perform well, but only when your team has the staffing and automation to respond within minutes.
Aged leads serve a different purpose. They can be productive when purchased at the right cost and worked through a disciplined outbound process, but they should not be priced or treated like fresh, exclusive opportunities. The trade-off is lower acquisition cost against lower initial contact and conversion rates.
Match lead delivery to your sales capacity. If your agents are unavailable during peak response periods, buying more fresh leads will not fix the problem. It will simply create more missed opportunities.
Audit the Source Before You Scale
Lead quality begins before a record enters your CRM. Ask how the traffic is generated, whether leads are exclusive or shared, what verification steps are used, and how duplicates are controlled. Ask whether campaign targeting can be adjusted based on your actual bind data.
A vendor that only reports lead count is not managing performance. You need visibility into source, delivery time, lead age, contact rate, quote rate, and cost per bound policy. The lowest cost per lead can become the most expensive channel when agents spend hours chasing consumers who never requested coverage.
For high-volume buyers, campaign control matters as much as lead quality. You should be able to set geography, product criteria, hours of delivery, daily caps, and pacing rules. These controls prevent your team from paying for leads it cannot service or cannot place.
Lead Flow Partners approaches this as a performance problem, not a volume contest. The right combination of real-time leads, live transfers, targeted data, and follow-up infrastructure depends on what your sales floor can convert profitably.
Build a Feedback Loop Between Sales and Acquisition
Marketing cannot qualify in isolation. The sales team sees the real objections, carrier limitations, contact issues, and policyholder concerns that form data never captures. If that information stays in call notes, lead generation will keep repeating the same expensive mistakes.
Create a regular review of lead outcomes by source and segment. Look beyond close rate alone. Compare speed to first contact, contact rate, quote rate, show rate where applicable, issued policy rate, cancellation rate, and customer acquisition cost. A source with a slightly higher price may be the better buy if it consistently produces policies that stay on the books.
Then act on the findings. Tighten targeting, revise questions, exclude weak ZIP codes, change delivery hours, adjust scoring, or route certain lead types to specialists. Qualification is not a one-time filter. It is an operating system that improves as sales data comes back.
The next time lead volume looks strong but revenue does not, do not ask only for more leads. Ask which prospects are reaching your agents, how quickly they are contacted, and whether your definition of “qualified” matches the policies your business can actually write.