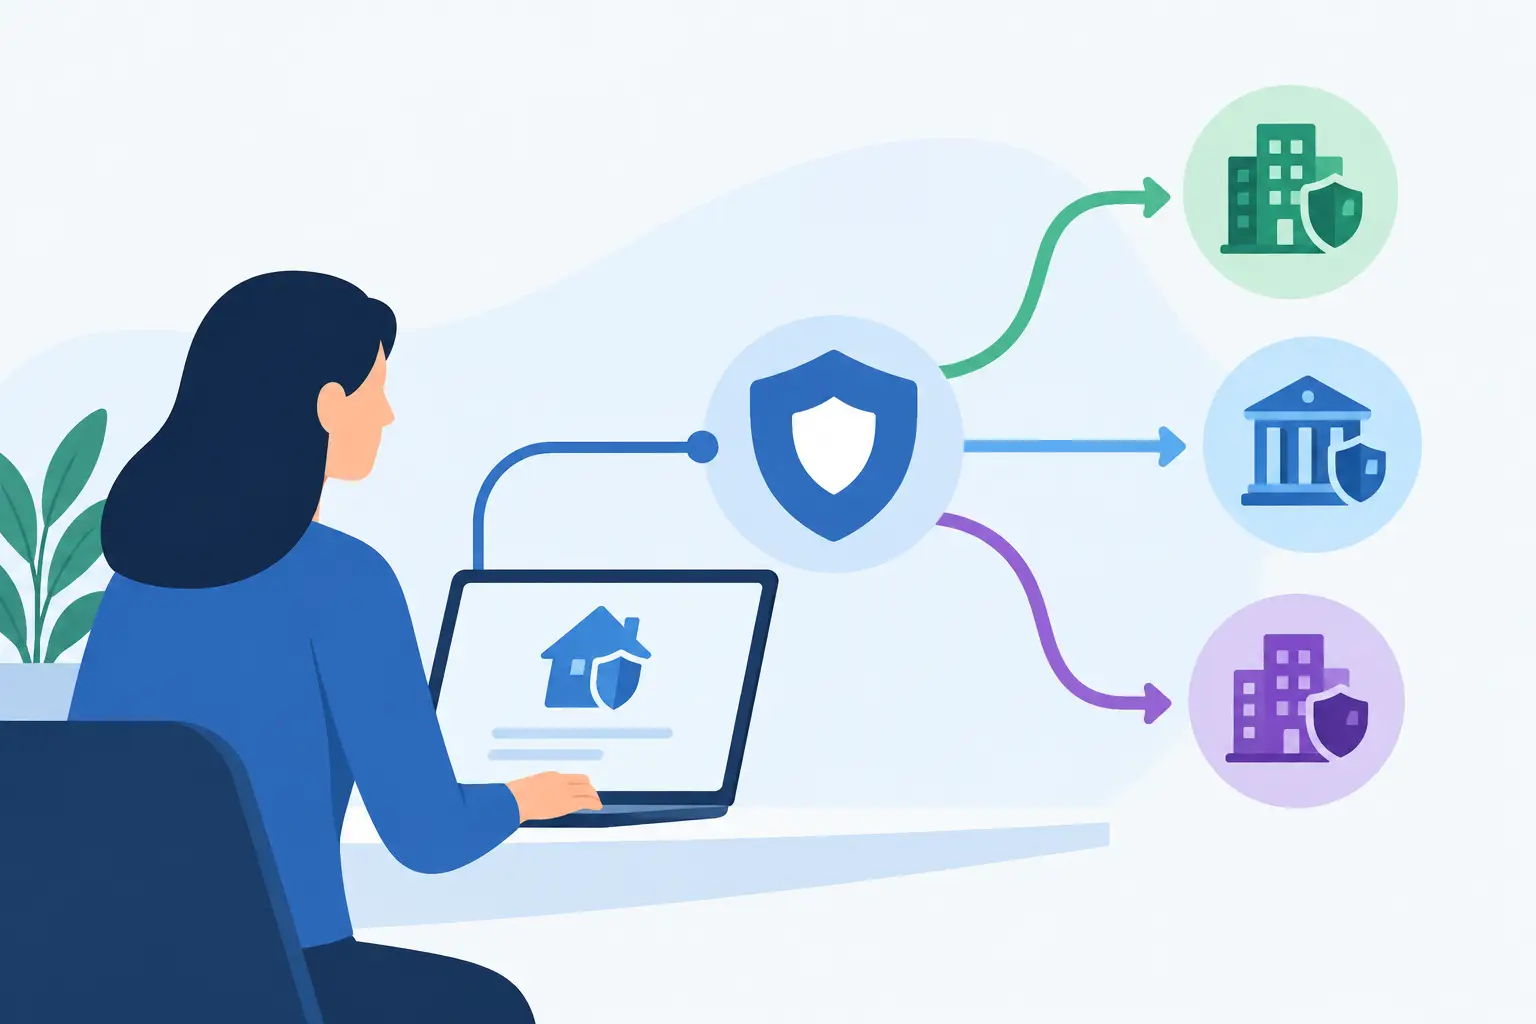
A $25 insurance lead can become a $250 problem when it reaches the wrong buyer, sits in a queue, or gets called after the prospect has already moved on. This insurance routing example shows how high-intent insurance traffic should move from form fill or live transfer to the agent most likely to quote, bind, and retain the policy.
The goal is not simply to distribute leads evenly. The goal is to make every lead decision based on eligibility, buyer appetite, agent capacity, compliance requirements, and expected revenue. That is how lead buyers protect margin while increasing contact and close rates.
An Insurance Routing Example That Protects Margin
Assume an inbound prospect requests an auto insurance quote. They submit their information at 10:02 a.m. on a weekday. The lead record includes their state, ZIP code, vehicle type, current carrier, coverage need, age range, household status, driving history answers, preferred contact time, phone number, and express consent details.
The routing system should not send that prospect to the next available agent by default. It should first determine whether the lead can be sold, who can sell it, and which destination has the strongest probability of converting it.
Step 1: Validate before distribution
The first layer is a quality and compliance check. Confirm that the phone number is valid, the state is serviceable, required consent language was captured, and the record does not match a recent duplicate. If the prospect is outside the buyer’s geographic footprint, lacks required information, or fails the campaign’s qualification rules, do not force the lead into a paid buyer queue.
This step protects agents from spending time on prospects they cannot write. It also protects the lead supplier from disputes that arise when a buyer receives traffic outside agreed campaign criteria.
For live transfers, validation happens before the handoff whenever possible. The caller should be verified against basic campaign requirements while they are still engaged. A transfer that arrives with missing consent, an unsupported state, or a disconnected number is not a premium opportunity. It is operational leakage.
Step 2: Match the lead to the right insurance buyer
Next, score the lead against each buyer’s active filters and performance history. Buyer A may want homeowners cross-sell opportunities in Texas and Florida. Buyer B may accept higher-risk auto profiles in selected states. Buyer C may pay more for clean-driving, multi-vehicle households but cap volume at 40 leads per day.
A practical routing hierarchy could look like this:
- Send the lead to an exclusive buyer that accepts the state, profile, and coverage type and has room for the lead.
- If that buyer is at capacity, route to the next approved buyer with the best expected revenue and recent conversion performance.
- If no real-time buyer qualifies, send the record into a compliant follow-up workflow or a designated non-live distribution path.
- If the lead is a duplicate, invalid, or outside campaign rules, suppress it from resale and document the reason.
The highest payout should not automatically win. A buyer offering $50 more per lead but answering 30 percent of calls may produce less revenue than a buyer that pays slightly less, responds immediately, and consistently binds qualified policies. Routing decisions should account for realized value, not just posted price.
Step 3: Assign to an agent who can act now
Once the buyer is selected, agent-level routing matters. A licensed agent who is available, approved for that state, and skilled in the relevant product should receive the opportunity first. For a live transfer, availability must be real, not assumed. If an agent has not answered recent calls or is already handling a customer, the system needs an immediate fallback.
For an internet lead, speed-to-lead is the operating standard. The first outreach should happen within minutes, not after the lead has passed through a manual spreadsheet, a generic inbox, and three internal handoffs. The prospect asked for a quote because their need is active. Your process should treat that timing as an asset with a short shelf life.
Step 4: Trigger a clear fallback path
Routing needs a failure plan. If the primary agent does not accept a transfer, fails to respond to a real-time lead within the required window, or reaches a daily cap, the lead should automatically move to the next qualified destination. There should be no ambiguity about who owns the lead or when ownership changes.
A basic rule might be: offer the live transfer to Agent Group A for 15 seconds, then Agent Group B for 15 seconds, then a staffed overflow team. For form leads, attempt delivery to the primary buyer, confirm receipt, and trigger an alternate route if the lead is rejected for a valid reason under the campaign agreement.
Fast fallback keeps high-intent prospects from dying in the gap between marketing and sales operations.
Build Insurance Routing Around Economics, Not Round Robin
Round robin distribution is easy to explain, but it often leaves money on the table. It assumes every agent, buyer, and lead has equal value. In insurance acquisition, that assumption rarely holds.
A stronger model ranks destinations using a weighted score. Start with hard requirements: state licensing, product eligibility, consent status, buyer caps, and hours of operation. Then layer in performance signals such as answer rate, first-contact speed, quote rate, bind rate, revenue per issued lead, cancellation rate, and dispute rate.
For example, a Florida auto lead may qualify for three active buyers. Buyer One pays $38 and has a 17 percent bind rate. Buyer Two pays $45 but has a 7 percent contact rate after 5 p.m. Buyer Three pays $35, answers nearly every live transfer, and has a 14 percent bind rate. Depending on the lead time and buyer capacity, Buyer Three may create the best expected return despite the lower stated payout.
That is the core routing calculation: expected revenue minus operational risk. A high payout that never converts is not premium inventory. It is expensive noise.
Use the fields that change outcomes
Do not collect data simply because a form can hold more fields. Collect and route on information that changes eligibility or agent strategy. In auto insurance, that can include state, ZIP code, vehicle count, current coverage, ownership status, incidents, and household composition. In health insurance, age, county, enrollment timing, and eligibility indicators may matter more.
Too few fields creates weak matching. Too many fields can reduce form completion and raise acquisition cost. The right balance depends on the product, traffic source, and whether the campaign uses real-time forms, inbound calls, or direct mail response.
Lead Flow Partners approaches this as a conversion system, not a delivery exercise. The media, qualification flow, buyer rules, and sales response process must work together if the campaign is expected to scale profitably.
Measure Where Leads Leak
Insurance routing should be audited like a revenue channel. If you only track leads delivered, you cannot see whether the routing logic is producing sales or merely moving records around.
Track the time from submission to first call, buyer acceptance rate, transfer connection rate, agent answer rate, quote rate, policy bind rate, revenue per lead, and the percentage of leads that hit fallback. Break those numbers out by source, state, buyer, time of day, device, and agent group.
A high fallback rate can signal that primary buyers are capped too tightly, agent availability is overstated, or the campaign is generating leads outside the strongest buyer appetite. A low contact rate may point to delayed response, weak phone verification, poor calling windows, or a mismatch between the lead promise and the sales script.
Do not wait for end-of-month reporting to correct these problems. A routing flaw can consume a week’s margin in a single busy afternoon. Review live performance frequently enough to shift caps, pause weak destinations, and direct volume toward buyers that are actually converting.
When One Routing Model Is Not Enough
There is no single routing model that wins across every insurance campaign. Exclusive leads usually justify more detailed matching and faster first-party follow-up. Shared leads may require tighter buyer caps and stricter duplicate controls. Live transfers demand immediate availability, while aged leads can support lower-cost, multi-touch outbound workflows.
The right setup also changes with campaign volume. A small agency may need a simple state-and-availability rule set. A large call center buying thousands of records weekly needs routing logic that accounts for licensing, product line, capacity, source quality, compliance records, and real-time buyer performance.
Start with a routing map that your sales team can explain in one minute: what qualifies, who gets priority, how long they have to respond, and where the lead goes next. Then improve it with real conversion data. The best routing system is not the one with the most rules. It is the one that gets qualified insurance prospects into productive conversations before your competition does.